Home / Rheal Software Blog / Exploring the Impact of Telematics and Usage-Based Insurance on Auto Claims: A Deep Dive into the Future of Auto Insurance
Exploring the Impact of Telematics and Usage-Based Insurance on Auto Claims: A Deep Dive into the Future of Auto Insurance
Published on May 03, 2024
Introduction
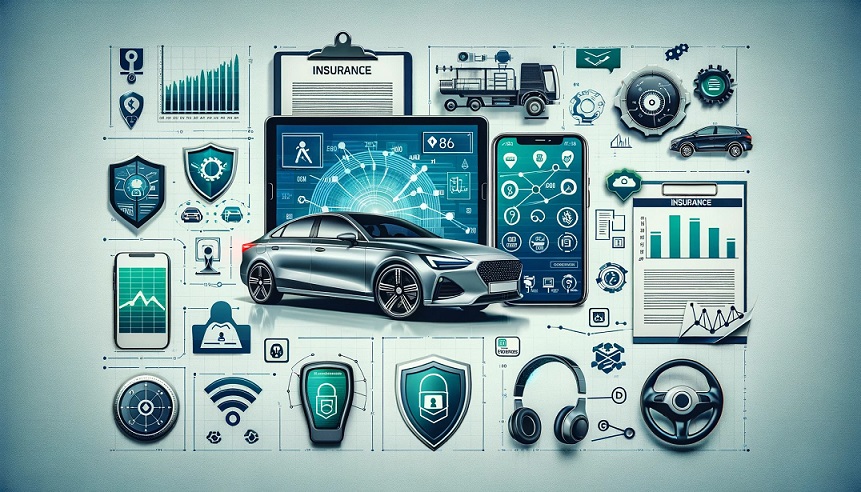
The landscape of auto insurance is undergoing a transformative phase with the integration of telematics and Usage-Based Insurance (UBI). These technological innovations are redefining the traditional models of insurance underwriting and claims processing. In this detailed exploration, we will unravel the multifaceted impact of telematics and UBI in the auto insurance sector, particularly focusing on their role in real-time data collection for efficient and accurate processing of claims related to accidents and driving behaviors.
Decoding Telematics and Usage-Based Insurance
To fully grasp their impact, it's essential to understand what these terms mean. Telematics is the integration of telecommunications and informatics, applied particularly in the automotive insurance field. It involves the use of in-vehicle telecommunication devices to send, receive, and store information. Usage-Based Insurance, on the other hand, is an insurance model where the costs are dependent on vehicle usage and driving behavior, as measured by telematics.
The Transformational Role of Telematics in Auto Claims
- Enhanced Claims Processing through Data: Telematics devices offer real-time data on speed, location, braking patterns, and more. This wealth of information allows insurers to process claims with unprecedented accuracy and speed, determining factors like the severity of an accident and the potential for injuries more precisely.
- Combatting Fraud with Precision: Telematics significantly diminishes the potential for insurance fraud. By providing exact data on where and how an accident occurred, insurers can easily identify inconsistencies in claims, safeguarding against fraudulent activities.
- Prompt Response and Assistance:In the event of an accident, telematics technology can automatically alert insurance providers, enabling a swift response. This immediate action can be crucial in ensuring timely assistance and support for the involved parties.
The Revolutionary Impact of UBI on Auto Claims
- Tailored Premiums Leading to Customized Claims:UBI promotes a more individualized approach to insurance premiums, which in turn affects the claims. Drivers with safer habits benefit from reduced premiums and potentially fewer claims, reflecting their lower risk profile.
- Promoting Safer Driving Behaviors: The knowledge that driving habits are being monitored and directly affect insurance costs encourages drivers to adopt safer driving practices. This behavioral change is expected to lead to a reduction in the number of accidents and, subsequently, claims.
- Dynamic Risk Assessment:UBI allows insurers to assess risk dynamically, adjusting premiums based on ongoing driving behavior. This dynamic approach ensures that premiums and claims are continually aligned with the actual risk presented by the driver.
Navigating Challenges and Ethical Considerations
The implementation of telematics and UBI is not without its challenges. Privacy concerns are at the forefront, as the constant monitoring of drivers raises questions about data security and personal privacy. Additionally, the reliability of the data and the technology itself are critical to the success of these systems in claims processing.
Expanding the Scope: Beyond Claims Processing
While the focus has been primarily on claims processing, the implications of telematics and UBI extend far beyond this area. These technologies are also playing a pivotal role in risk management, customer engagement, and policy personalization, offering a more holistic approach to auto insurance.
- Risk Management and Prevention: Telematics data enables insurers to not only assess risk more accurately but also to anticipate and prevent potential incidents. By analyzing driving patterns, insurers can identify high-risk behaviors and offer targeted advice or training programs to mitigate these risks.
- Enhanced Customer Engagement: With UBI, insurers can maintain continuous engagement with their customers. This ongoing interaction provides opportunities for insurers to offer value-added services, such as personalized driving tips, vehicle maintenance advice, and rewards for safe driving habits.
- Policy Personalization: The data collected through telematics allows for unprecedented levels of policy customization. Insurers can tailor policies to suit the specific needs and risk profiles of individual drivers, moving away from the one-size-fits-all approach.
The Technological Backbone: Ensuring Reliability and Security
The success of telematics and UBI hinges on the robustness of the underlying technology. Ensuring the reliability and security of data collection, transmission, and storage is paramount.
- Data Accuracy and Consistency: The effectiveness of telematics-based claims processing relies on the accuracy and consistency of the data collected. Continuous improvements in sensor technology and data algorithms are essential to maintain high data quality.
- Cybersecurity Measures: With the increasing amount of data being transmitted, cybersecurity becomes a critical concern. Insurers must invest in advanced security protocols to protect sensitive customer data from breaches and cyber-attacks.
- Compliance with Regulations: As telematics and UBI evolve, they must comply with evolving regulations and standards, particularly those related to data privacy and protection. Navigating these regulatory landscapes will be crucial for insurers to maintain customer trust and legal compliance.
Case Studies: Success Stories in Telematics and UBI
To illustrate the impact of telematics and UBI, several case studies can be highlighted. These success stories showcase how insurers have successfully implemented these technologies to enhance claims processing, improve risk assessment, and increase customer satisfaction.
- XYZ Insurance's Accident Response Time Reduction: XYZ Insurance utilized telematics to reduce their accident response time by 50%, significantly improving customer satisfaction and reducing claim costs.
- ABC Auto Insurance's Risk Assessment Model: ABC Auto Insurance developed a dynamic risk assessment model using UBI data, resulting in a 30% reduction in claims over a year due to improved risk mitigation strategies.
- DEF Insurance's Customer Loyalty Program: DEF Insurance launched a customer loyalty program based on safe driving scores from telematics data, leading to a 20% increase in policy renewals and enhanced customer engagement.
Conclusion
Telematics and Usage-Based Insurance are set to revolutionize the auto insurance industry. They represent a shift towards more data-centric, personalized, and efficient claim handling processes. As these technologies evolve, they promise to bring even greater accuracy and efficiency to the sector.
The integration of telematics and Usage-Based Insurance into the auto insurance sector represents a significant leap forward in how insurers assess, process, and manage auto claims. By harnessing the power of real-time data, insurers can offer more personalized, efficient, and fair services, marking a new era in the insurance industry. As these technologies continue to evolve, they promise to bring even more profound changes, making auto insurance more aligned with the individual needs and behaviors of drivers.
ABOUT THE AUTHOR
RELATED ARTICLES
Chatbots for Claims Assistance: Revolutionizing the Insurance Claims Process with AI
Discover how AI-driven chatbots are transforming the insurance industry by streamlining claims reporting and processing, bringing efficiency and enhanced customer satisfaction to the forefront of insurance services.
Blockchain for Claims Transparency: Revolutionizing Property and Casualty Insurance Claims
Explore how blockchain is transforming the insurance industry, providing unprecedented transparency and security in claims processing. Discover how this technology helps combat fraud and ensures a reliable claims history.
Insurtech Innovations: Reshaping the Insurance Landscape Through Technology and AI
Explore how Insurtech, a convergence of insurance and technology, is revolutionizing the traditionally slow-moving insurance industry. Delve into how technology and AI are not just reshaping but fundamentally reinventing the insurance landscape.
Climate Change and Insurance: Navigating Risks with Technology and AI
Explore the impact of climate change on property and liability insurance. Discover how insurers are leveraging technology and AI to navigate the challenges posed by the increasing frequency and intensity of extreme weather events.
Revolutionizing Claims Assessment: The Game-Changing Role of Drones in Property Damage Evaluation
Explore the transformative impact of drones on property claims assessment in the insurance industry. Discover how unmanned aerial vehicles are reshaping damage evaluations, particularly after natural disasters.
Blockchain in Insurance Revolutionizing Property and Liability Coverage
Explore how blockchain technology is revolutionizing property and liability insurance, offering solutions to challenges such as fraud, inefficiency, and lack of transparency.
Claims Automation and Artificial Intelligence Revolutionizing Property and Casualty Insurance Processes
Explore how the integration of Artificial Intelligence (AI) and automation is reshaping the landscape of property and casualty insurance, enhancing efficiency, precision, and reducing claims processing time.
If You Are In Need of a Reliable Outsourcing Partner, Try Our Services Risk Free!
- Start with a free no obligation consultation to discuss your business needs.
- We will advise you on how we can help you. You can then try our services risk free for a 100 hours.
- Pay only if you are satisfied. Otherwise, you owe us nothing, no questions asked.

Thank you for submitting your inquiry for our 100 hour Risk Free Trial.
We will get back to you shortly.
Please try again.